Category: Real Estate Best Practices

  • New Open Offices Result in Increased Employee Attendance

    New Open Offices Result in Increased Employee Attendance

    Littler measures improvement one badge swipe at a time

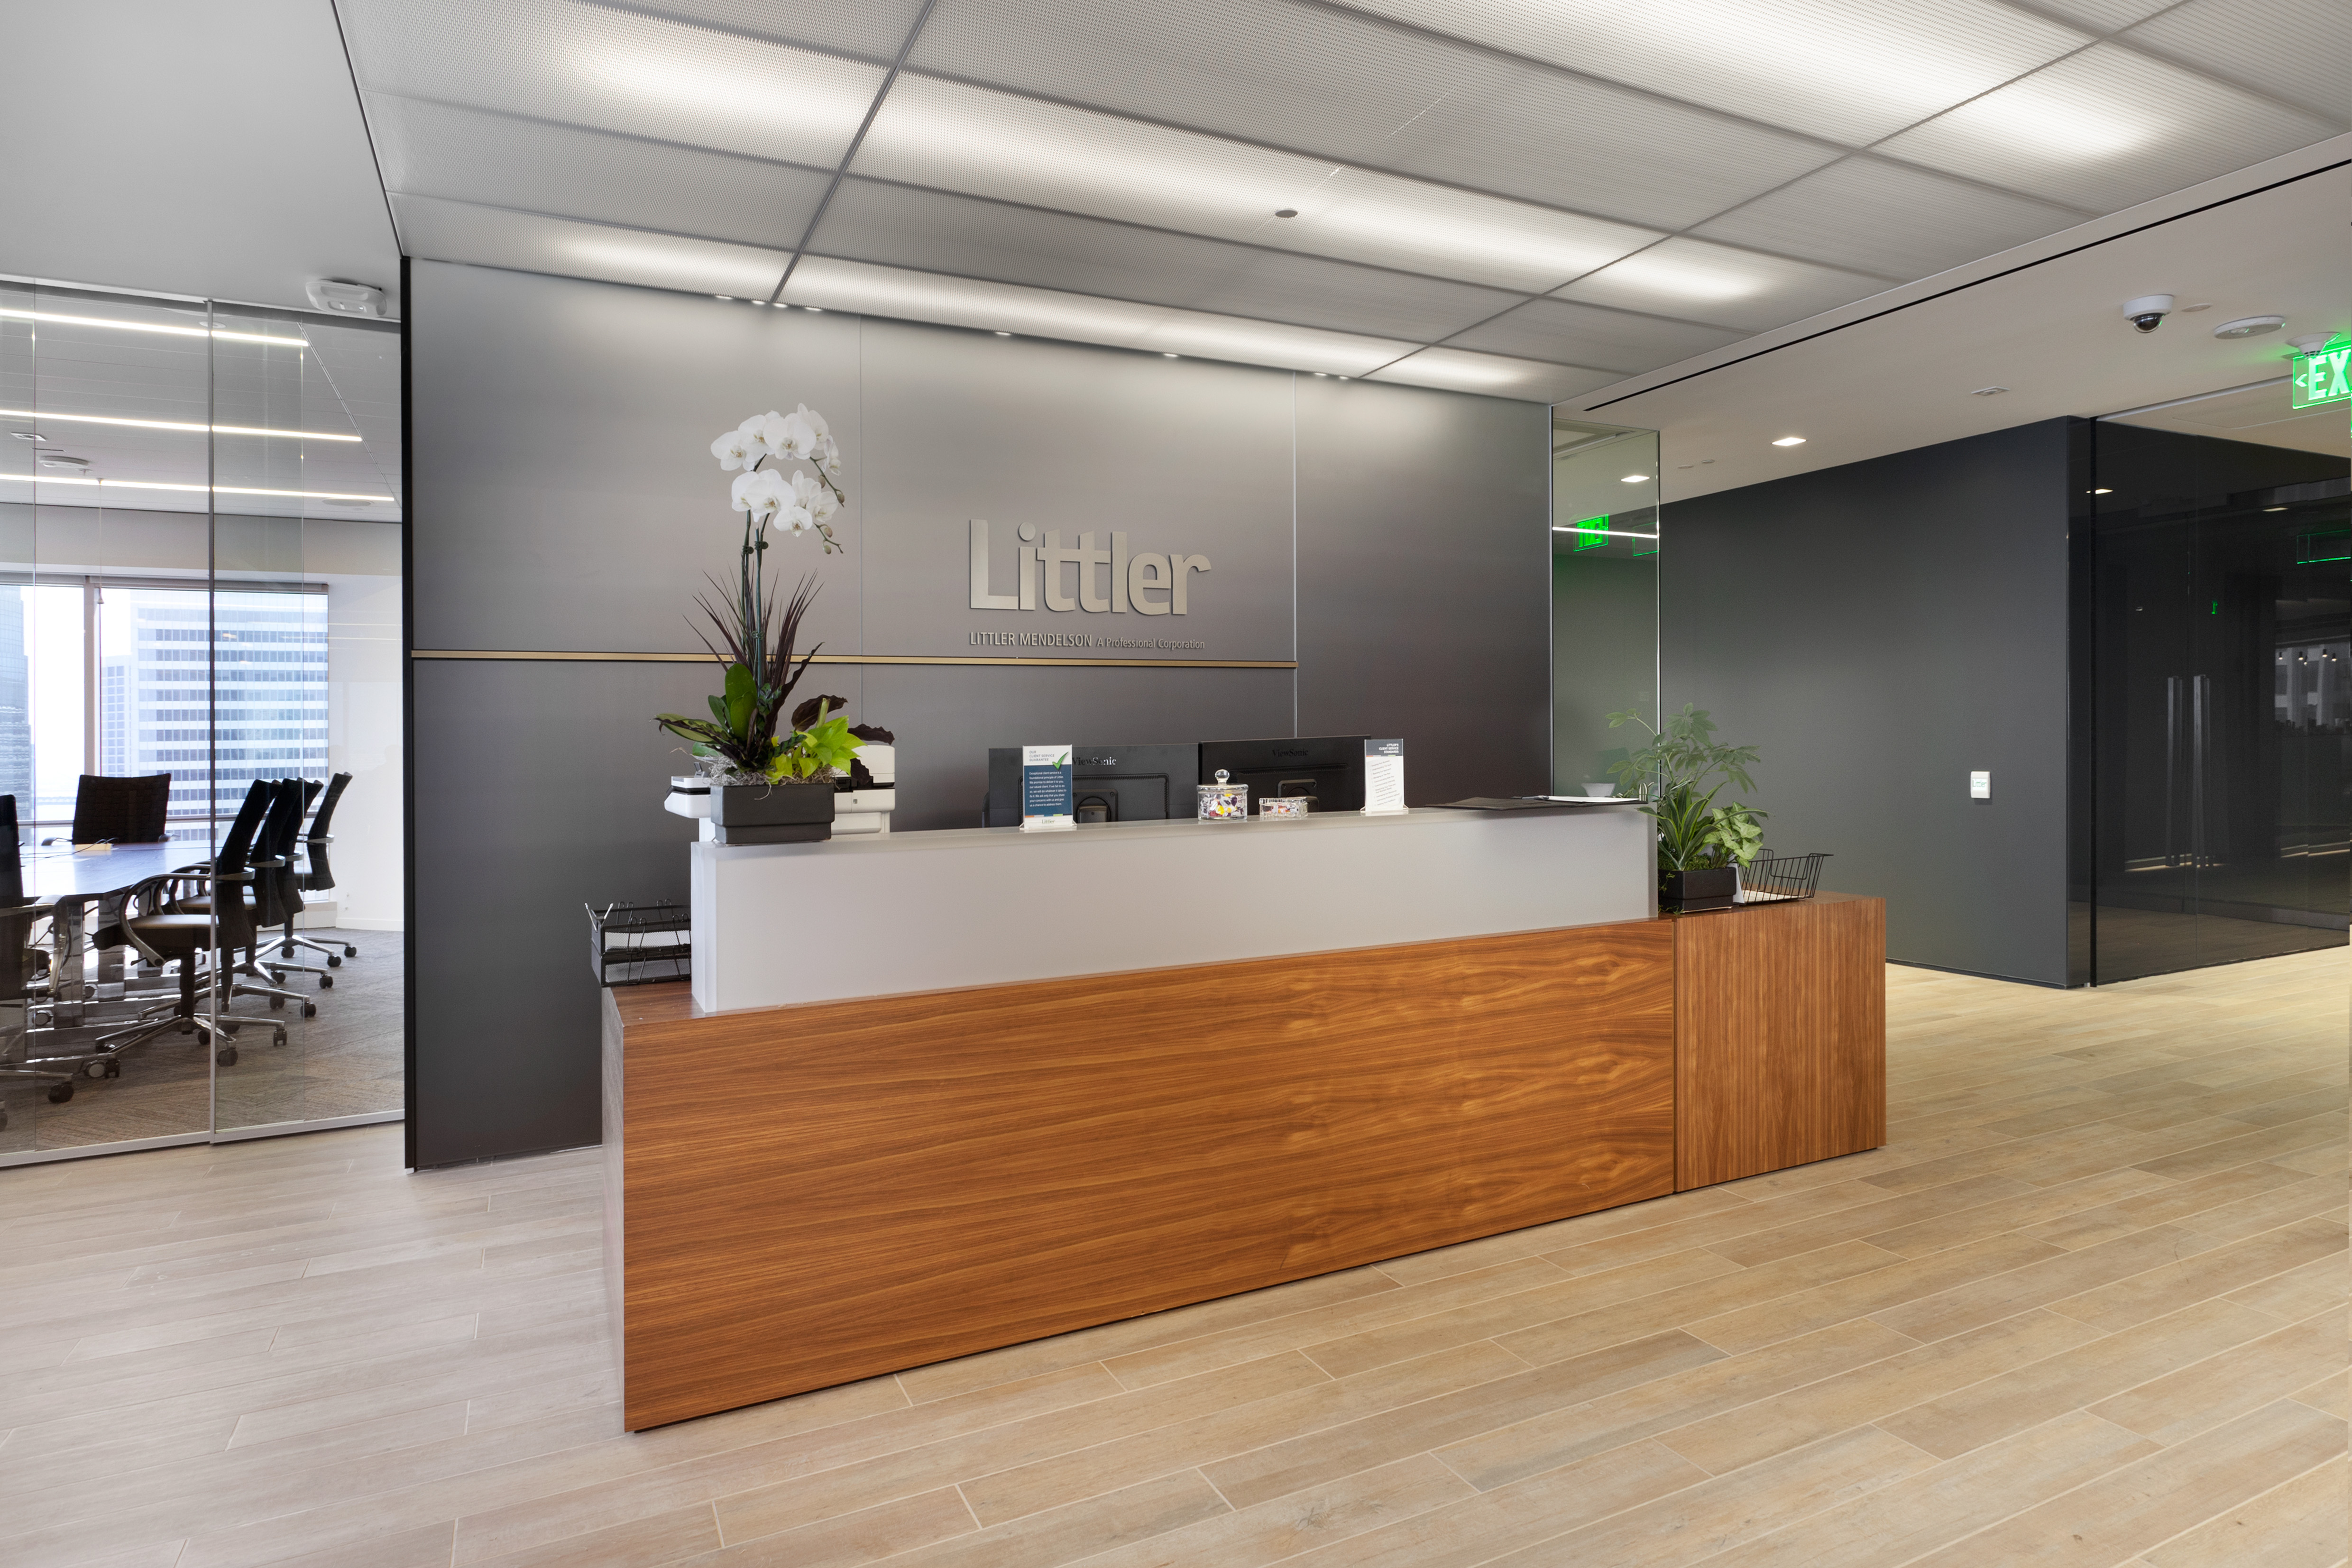
    Last year, after more than forty years at 650 California Street, law firm Littler Mendelson moved their San Francisco offices to 333 Bush Street.  The new design included standard sized offices of ~120 square feet with glass walls and low-height cubicles to maximize sight lines and interaction.  These open and airy new offices were built to maximize natural light and promote collaboration and interaction.

    Before and after the offices were built, Littler’s administration tracked how many days per week each San Francisco employee badged in and out of the office.  For instance, if an employee worked Monday through Friday every week, their attendance was 100%.  If they worked Saturdays as well, attendance was 120%.  This information was not tracked to spy on individual employees but rather to determine whether office attendance increased with the new build-out and if so, whether the increase was consistent across all roles – data entry clerks, accounting professionals, associates, partners, etc.

    What did they learn? Attendance across all roles increased in the new leaner but brighter space.  Essentially their employees voted in favor of the new space with their increased desire to be in the office.  Littler can now use this data to help sell the firm’s new space standards across their portfolio.

    Since increased office attendance was a goal with their new office space, this metric was the perfect measure.  What metrics might you use to measure the effectiveness of your space?  It depends on your goals but, like Littler, you may already have access to the data you need to track.

    To read about the novel way Littler assigned individual offices within this new space, click here.

  • Four Real Estate Benchmarks You Should Track and Why

    Four Real Estate Benchmarks You Should Track and Why

    If you are a business owner, services firm manager or corporate real estate director, you likely have some strategy regarding your real estate.  That strategy could be to contain costs, or to encourage interaction and collaboration between employees, or to ensure that you have sufficient flexibility to grow, shrink or relocate as your business requires.  In order to assess whether your strategy is working (and get buy in from the executive team), you need to determine which metrics measure strategic success and then start benchmarking those metrics over time internally and against your industry. 

    Which Metrics Should You Use?

    There are a number of them that we recommend, including:

    1)     Square feet per employee: To determine this number, divide the total square footage your company owns or leases and actually OCCUPIES (exclude subleased space) by the total number of employees.  A simple lease tracking system can provide you the square footage numbers.  In the absence of such a database, the accounting people who pay rent or the attorneys who negotiate the leases usually have this data.

    You can also determine this ratio for each separate location.  This data can be used in several ways.  Some of our service provider clients compare the overall portfolio ratio with each office’s individual ratio to identify those offices that are significantly above or below the average.  Those offices may provide opportunities to right-size the space and improve portfolio efficiency.

    Other clients use this number to compare themselves to their industry.  Industry benchmarks for square foot per employee can be found in the International Facility Management Association’s (IFMA) annual benchmarking report or can be obtained from your real estate services provider.  For instance, the IFMA average for insurance industry occupiers may be 200 square feet per employee.  If you are an insurance company and you average 300 square feet per employee, the reason for the difference may be worth investigating and incorporating in your strategy.  If your strategy then becomes densification, you can compare your square feet per employee at the end of next year to this year’s number to determine whether the strategic decisions you made improved this metric over the year.

    2)     Real estate cost per employee: It is the total real estate cost per employee divided the total number of employees.  To make this number meaningful, you need to define real estate cost.  It can include rent, operating expenses, utilities and/or taxes across the whole portfolio. To be meaningful, the components included should be the same year over year.  The data can usually be obtained from the accounting department at your organization.

    The real estate cost per employee is a great way to evaluate the relative cost of different locations.  For example, a law firm leasing five thousand square feet in downtown Manhattan for ten lawyers may pay $50,000 per lawyer for space.  If that same firm leases fifty thousand square feet in Birmingham for 100 lawyers, the cost per lawyer is $10,000.  The square feet per lawyer (500) is the same in both offices.  However, an improvement in the density of the Manhattan offices will produce an exponentially greater reduction in costs than that same improvement in Birmingham.  The law firm can use this data to identify high value cost savings opportunities.

    3)     Internal vacancy rates (how many unassigned seats do you have?):  To calculate this number, you need a seat count for each office as well as a headcount.  The criteria for determining the number of seats should be defined. For example, it could be one seat per workstation or office.  Conference and huddle room seats should not be counted unless they are used primarily as regular workspaces.  IT can be helpful in determining seat count as they can usually tell you how many phone lines or handsets are deployed and how many of those have numbers/employees assigned to them.

    Once determined, this seat count can then be divided by the total number of employees to determine what percentage of your seats are vacant.  Depending on the volatility of a business and its growth plans, optimal vacancy rates may be as close to zero as possible or as high as 10-15% to allow for fast growth.

    If you have a badge security system, you can also determine how many employees on average are in the office on a daily basis.  This information can help you understand whether those assigned seats are actually being occupied by their assigned employee each day.  In industries like accounting this data has been used to justify a hoteling strategy where some of the seats are left unassigned and may be used by any employee in the office on a given day.

    4)     Employee attendance, productivity and satisfaction: These measures are more subjective but they can help you identify strength and weaknesses in your workplace design and operation.  They can also be utilized to gauge whether a change made to improve design or operations was effective.  When Deloitte built out 500,000 square feet in a new, highly-amenitized building in Toronto, the number of employees going into the Toronto office to work (rather than working remotely) sky-rocketed.  Because this increase was a desirable to Deloitte, they used this data to help them refine their strategy for future locations to focus on amenities.

    Your real estate,whether a single location or a multi-market portfolio of properties and leases, is a significant asset and cost to your organization. It houses your employees, facilitates the operation of your business and brands your company to your clients. An evaluation of the metrics of your real estate can help you understand where you are and provide a benchmark for measuring future success.

  • Building Sale + Land Sale + Furniture Sale + New Office Lease = Wisconsin Fun With ProAssurance

    Building Sale + Land Sale + Furniture Sale + New Office Lease = Wisconsin Fun With ProAssurance

    I hope everyone shares this sentiment, certainly for me, 2016 was a fun year.  Professionally, with my partner, Joe, I was able to complete some interesting transactions that created a ton of value for our clients.  One of the highlights was a project I worked on with our client, ProAssurance, and its director of real estate, JC Blakely. 

    We have been working with ProAssurance for several years and as part of that strategic partnership, we monitor their real estate portfolio for opportunities to save them money and/or create value.  ProAssurance’s portfolio includes some owned buildings across the country acquired through a various mergers and acquisitions.  Recently, some of the operations previously handled out of one of these buildings, a 35,000 square foot office building in Madison Wisconsin, were consolidated to another location.  This meant that ProAssurance had an opportunity to sell the building and relocate to an appropriately-sized space in a building with more amenities.  The building came with a few acres of cropland adjacent to the building and ProAssurance had been leasing that cropland to a farmer.

    We partnered with a local Madison broker with whom we had worked previously — Mike Herl.  Because the land and the building were in a developing area of Madison, we thought there was a great opportunity to sell both the building and the land at a great price for ProAssurance.

    In order to ensure that there were no negative tax consequences associated with the sale of cropland due to its likely conversion to commercial development, we identified a qualified WI tax lawyer to advise on the process.  Once that hurtle was cleared, we placed the property on the market.

    Several buyers were quickly identified and two offers were received.  We negotiated on the best overall offer while also working to secure leased replacement space for ProAssurance.  Because the buyer wanted to close quickly, we negotiated a leaseback post-sale until ProAssurance’s new space could be built out. We were also able to negotiate the sale to the buyer of ProAssurance’s fully amortized furniture inventory.

    The building brought a purchase price of $4.7M and the cropland brought an additional $1.75M.

    The sale and relocation resulted in a 70% net reduction in ProAssurance’s occupied space in Madison and operating costs were reduced significantly.  In addition, in the new location, all employees will be located on the same floor in modern space built to increase collaboration.  Finally, ProAssurance will no longer have to provide facility management for a building remotely located and not fully occupied. Working on a team so focused on getting the best result for ProAssurance made all of the challenges associated with selling a building, structuring a lease back on a portion of the space and negotiating for a relocation site worthwhile.  It is rewarding to watch it all come together and I can’t wait for the next challenge in 2017!

    Photo credit: CommercialSearch.com 

  • 2016 Blog Year in Review

    2016 Blog Year in Review

    Ten years ago, I was contemplating changing employers after almost ten years at the same company.  I called my wise and fearless friend, Craig McKesson, for advice and he told me “if you’re not growing, you’re dying”.  Please know that my modus operandi up to this point was to take the safest route, so this advice was tough love.  Nonetheless, I made the change and I grew and it was fantastic.  Even better, I learned how much fun change can be.  So, earlier this year and in keeping with this philosophy, I started writing this blog.

    I have traveled coast to coast and covered a variety of subjects hopefully of interest to everyone from my fellow real estate brokers to law firm COOs to tech company founders.

    In the legal realm, I talked about whether law firms could benefit from having  advisory boards made up of non-lawyers.  My partner and I also surveyed in-house counsel at 32 large companies and shared what we learned from them about what they are looking for from outside counsel.

    I also get into law office design and space issues including Littler Mendelson’s new 120 square foot offices and their novel approach to determining who gets the good office.  Here’s a brilliant idea to create more space in an existing law office.  This post may help law firms plan their space to evolve with their business and this post can help them decidewhether or not associate opinions matter in the design of law firm space.  I toured a local example of a progressive law firm buildout and got some great ideas from a not-so-local firm, DLA Piper.  Finally, with some help from my partner, Joe, I examine whether a professional services firm should own its own building or the one next door.

    Start-up founders and those interested in progressive office space may want to read Parts 1, 2, 3, 4 and 5 of my series on San Francisco’s tech spaces.  For an East Coast rendition of this West Coast adventure, read this post about building for serendipity at Google NYC.  If you are trying to build a great company culture, read this post about fun employee perks.  If that culture might include a distributed workforce, read this post about local fast-burner, Fleetio.

    If you develop or redevelop real estate, please read this post about the importance of “place”  as learned from Brookfield Properties and this one about making the most of older buildings.

    If you manage a corporate real estate portfolio, please read this post about why you need renewal rights and then this article about the effect of the new FASB rules those rights.  For help preparing for the onslaught of operating expense reconciliations you will be receiving first quarter, read this post – Operating Expense Desk Audit 101.  If you are a property manager seeking to justify your existence, read this article about the importance of your role in the real estate eco system.

    If you own property, this blog post is a reminder about the importance of up-to-date CAD files.  And this, my most-read post (written by John Pickering), discusses whether employers or building owners can ban guns from the office.

    If you are a real estate lawyer or broker, you might want to read this post about whether a witness is required on your lease or this one which details whether an email can modify a real estate lease or sale contract.  This post give a quick overview of five areas often overlooked when closing a real estate sale.  If you are working on a lease for new construction, you might find some helpful hints here.

    I will leave you with two of my favorites:  this post about the value of surprises and this post about the importance of ending on a high note.  Thanks for 2016.  See you next year!

  • The Value of Surprises

    The Value of Surprises

    Surprises and vivid action matter far more than we imagine, and we regularly underinvest in them.  – Seth Godin

    I read this quote earlier this year and in reflecting on 2016, I am overwhelmed by its truth.  For me, the high points of the past year almost all embody at least one of these two characteristics.  As examples:

    ·         Receiving two small brass elephant bookends hand delivered to my house on the date of the SEC championship by friends who just knew that I would love them.  (Roll Tide!)

    ·         Reading a text from a vacationing client thanking me for my efforts on behalf of him and his company.  Incidentally, this is not the first time he has done something thoughtful like this.  And I would do anything for someone who treats me like such a valued partner.

    ·         Arriving to work to find a large bag of my favorite dark chocolate with a kind note from a co-worker who makes my life easier on a daily basis.

    ·         Enjoying a lovely dinner out with my husband compliments of my partner who appreciated my work on a deal.

    ·         Opening my mail to find an article that one of my blog readers thought I would find interesting.

    ·         Being awarded a Colliers Blue Mont Blanc pen in recognition of a career milestone at a staff meeting.

    ·         Having a friend who could give Martha Stewart competition come to my house at noon laden down with tableware to set a beautiful table for me for a party I had planned in the evening.

    The common thread?  When we are surprised, we recognize that someone was thinking of us and cared enough to let us know. And that feeling has staying power.  We may forget an offhand spoken “thank you”, but we usually bask in reading a well-written thank you note.

    I have made a concerted effort this year in both my personal and professional life to let friends, family and clients know that I am thinking of them and value them. This might be the most important part of my job.  Have you been on the giving or receiving end of surprises and vivid action?  Do you agree with this quote?

  • Operating Expense Desk Audit 101: How to Make Sure You Aren’t Overpaying

    Operating Expense Desk Audit 101: How to Make Sure You Aren’t Overpaying

    If your firm or company leases office space, the odds are good that you pay your landlord for actual annual increases in the cost of running the building.  Leases are either set up (1) to include a base amount of operating expenses in the rent (usually equal to the actual total costs in the first year of the lease term) and in subsequent years, the tenant reimburses the landlord for actual costs in excess of that base year amount (“full service”) or (2) to exclude these amounts from rent but allow for separate reimbursement from the tenant for all operating expenses incurred by landlord (“net”). 

    Whether net or full service, the landlord usually estimates operating expenses for the coming year and the tenant pays 1/12 of that estimated amount each month during the year.  After the year ends, the landlord reconciles what was actually spent to operate the building with what the tenant paid over the year.  The tenant then either pays any shortfall or is issued a credit for any overpayment against rents coming due.

    These reconciliation statements typically arrive at the end of the first quarter and often accounting departments pay them without review.  However, in my experience, it is worth taking a little time to do a quick audit of the statement.  Here is our approach:

    1.       If your lease is full service, make sure that the base year reflected on the statement is accurate.  Oftentimes a company will add expansion space over their lease term and that space will have a different base year than the original space. Or, if a lease is renewed and the tenant is given a new base year, occasionally the reconciliation reflects the original base year which is lower, resulting in more cost to the tenant.  It is worth confirming that all base years are correctly stated.

    2.       Check “gross ups”.  Most leases provide that tenants pay their proportionate share of operating expenses based on their share of the total building square footage.  So, if a tenant occupies 40,000 square feet in a 100,000 square foot building, the tenant pays 40% of the total operating expenses for the building.

    However, some expenses, like janitorial, are variable.  For instance, if 20,000 square feet are vacant in that same 100,000 square foot building, the landlord is not going to pay to have that space cleaned every day; the landlord is only going to pay to clean the 80,000 square feet of occupied space.  So, if the tenant pays its pro rata share (40%) of the actual janitorial costs incurred, that tenant is essentially paying for 32,000 square feet of cleaning which is less than  the appropriate cost.  As such, most leases contain clauses that allow the landlord to gross up variable costs to reflect a fully occupied building.

    In reviewing gross ups, make sure expenses being grossed up by the landlord are truly variable. Variable expenses are often specifically defined in the lease and usually include janitorial costs, management fees and utilities which understandably fluctuate with occupancy levels.  When we see landlords gross up taxes, we will question it because taxes do not get reassessed each year based on the occupancy rate in a building. Similarly, grounds maintenance should not get grossed up because grounds have to be maintained to the same standard regardless of occupancy levels.

    3.       Compare last year’s itemized costs with this year’s.  Have any expense categories increased by an inordinately large percentage compared to the other categories?  If there is not a simple explanation for it, i.e. utility rates increased, it is worth asking the property manager for more information.

    4.       Are there any new categories of expenses reflected on the reconciliation that were not included in previous years?  I had one client receive a reconciliation billing them for “lobby art”.  Their lease specifically provided that artwork was a landlord expense and could not be passed through to the tenant so the tenant was able to remove that $20,000 expense from their bill.

    5.       Is the math correct?  Sounds simple but I make mathematical errors regularly and property managers are fallible too.

    6.       Check for capital expenditures.  Most leases do not allow landlords to include capital expenditures in operating expenses unless they increase the operating efficiency of the building thereby decreasing operating expenses over the long term.  If your lease has language like this and there is a large capital cost included on the reconciliation, it is worth a friendly call to the property manager to get more information about the nature of the expense.

    As our team reviews reconciliations on behalf of our clients, we try to keep in mind the long-term nature of the landlord/tenant relationship; we want everyone to get along over the life of the lease.  As such, our approach is always collaborative in nature as we know most overcharges are inadvertent and usually quickly remedied by the property management team.  Is there a something I missed?  I would love to hear your comments! And, if you would like to download my list of operating expense exclusions, go to this page.
  • The Disconnect Between Lease Term Length and Business Forecasting

    The Disconnect Between Lease Term Length and Business Forecasting

    The information age has increased the velocity of change exponentially.  Think about it: most businesses now build a two-year strategic plan – best case.  And most can only project revenue one year out because business owners don’t know how their businesses are going to evolve.  Take Instagram.  It started as a small app that allowed its users to “check in” at various locations so their friends could find them.  The founders of that tiny little start-up had no idea that the photos incidental to that service would make their business explode into one of the biggest businesses in Silicon Valley.

    What do these evolving businesses need most when they are looking for office space?  Flexibility of term and flexibility to grow or shrink in size.

    Now think about real estate.  Most landlords buy buildings with financing made available to them only because those loans are secured by long term leases with credit-worthy tenants (not the Instagrams of the future).  Today, however, even creditworthy Fortune 500 companies have difficulty predicting their futures with any certainty.  Did you know that the average lifespan of an S&P 500 company has decreased from 67 years in the 1920’s to 15 years today?  What happened to Kodak?  Radio Shack?

    So how do we reconcile the needs of many of today’s businesses with the requirements of owners and mortgage lenders on commercial office buildings?   It seems like the answer to this question might be a compromise on behalf of both landlords and tenants.

    Tenant Compromise

    Growing companies searching for office space need to understand that the more money they ask the landlord to put into building out their space, the harder the deal is for the landlord.  If, however, a tenant takes space “as is”, the landlord does not have to come up with any capital upfront.  Less deal costs and less risk.  So, if the tenant fails and defaults on its lease, the landlord has significantly reduced its exposure.   The same goes for a tenant that needs to relocate because of growth-fueled expansion requirements

    On the other hand, if a tenant asks a landlord to build out large numbers of private offices and use high end finishes, the landlord is going to require a longer term length over which to amortize the costs of those improvements.  A landlord is also going to want some security for its investment and most young companies cannot offer that.

    Landlord Compromise

    Landlords could provide very open floorplan space with open ceilings and perhaps one enclosed room per 1500 square feet for use as conference or huddle space.  If tenants embrace an open floorplan, the electrical and HVAC ducting do not have to be reconfigured every time a new tenant occupies the space.  Because the landlord’s investment is low, his exposure is low.  The landlords are more able to agree to shorter term leases that allow tenants the flexibility they need to grow.

    Landlords should also recognize the fact that many young start-up companies eventually become their full-floor tenants.  Jeremy Moss of Silverstein Properties shared an anecdote about his experience as a landlord.  Silverstein converted half a floor at 7 World Trade Center to a flex “incubator” space which would house small tenants for short terms.  It was very successful for them.  One tenant from that initial space is now a two-floor tenant in the building.  And, Silverstein went on to convert another entire floor to this incubator concept.

    In summary, if tenants embrace a more open plan and customize their space with furniture and décor which they own and which can be easily relocated as their needs evolve, landlords should be able to provide greater term flexibility in exchange for the lower build out costs.

  • Thanksgiving Thoughts: Go and Do

    Thanksgiving Thoughts: Go and Do

    It’s Thanksgiving week and no one wants to read about office space metrics or service firm operations. Instead, I am going to share my biggest lesson learned in 2016: Go and Do.

    As any of you who read this blog on a regular basis know, this year has taken me to Washington, DC, New York, Nashville and San Francisco.  I have attended conferences, visited with clients, landlords and developers and toured many office spaces.  And I have learned so much that I wouldn’t have sitting in my office.

    I learned that people are usually very willing to help other people when asked.  I reached out to the alumni networks at my various alma maters, friends, architects, colleagues, former colleagues and clients to get access to tour spaces at companies where I knew no one.  I received tours from complete strangers who were kind enough to show me every inch of their spaces and answer all of my questions.

    I learned what draws people to work at different companies and in different spaces.  I learned novel approaches to solving real estate and facilities problems.  I learned how different industries see the future and what it might mean for office space.  I also learned how to process all of this information and turn it into knowledge I can use.  Clearly, I synthesize information by writing and thus, this blog.

    I hope you are enjoying it half as much as I enjoy writing it.  So much more to come!  

  • As Cities Grow, Property Management More Important

    As Cities Grow, Property Management More Important

    – Guest Blogger, Tommy Hiltz, Colliers International

    When I tell people my company does property management, I get plenty of pleasant, vacant smiles. The truth is, not many people know what we do, how we do it, or even why we are needed. Many people have violent flashbacks to the front office workers at their first apartments, who refused to acknowledge broken appliances or leaky faucets. In their mind, we represent that worker, albeit a bit nicer and hopefully more responsive. Our purpose remains associated with negative occurrences and retroactive inadequacies. Yet property management can justify itself in tangible ways not only to owners, but to tenants, employees, and customers.

    While the scope can be as wide as the “management” implies, the property manager faces three main objectives:

    1.    Handle unforeseen events
    2.    Assist with future planning
    3.    Oversee expansion

    1.     Handle unforeseen events – A roof of a multi-tenant office building leaking during a thunderstorm is a bona-fide nightmare for all parties involved.  Tenants might try to call the owner, who could be an institutional investor which, due to its remote location, is functionally incapable of handling the emergency.  The tenant might then search the internet, praying that whomever they call does quality work as rain water continues to pool on computers, carpeting, machinery, and equipment.  Property owners engage property managers to avoid this scenario.

    On any given day, we are called to deal with cracked windows, burst pipes, broken air conditioning units, and countless other problems.  Property managers can offer a painless resolution to harrowing situations by being prompt and flexible, bringing detailed experience and a robust rolodex of professional service providers.

    2.    Assist with future planning- A critical aspect of property management is preserving the value of the building for the future.

    Because we spend so much time at the properties, we have an intimate knowledge of current conditions that enables us to plan repairs and property improvements and budget with accuracy the properties performance.  While some of these expenses, such as Maintenance and Repairs, require us to make educated estimates that account for risings costs and different circumstances, others can be more intricate.

    Our planning often involves large capital outlays such as renovations, expansions, or freestanding construction.  If an owner has an opportunity to increase the return on investment (ROI), internal rate of return (IRR) or resale value, the property manager is in a great position to point out that opportunity and then oversee implementation of the plan

    3.    Oversee expansion- Many owners feel unequipped to evaluate the financial merits of a possible project and many lack the time or knowledge to oversee the physical implementation of said project.  The property manager can coordinate with the owner, contractors, subcontractors, and other involved parties to ensure that projects run not only on-time, but at or under budget.  At Colliers, we routinely oversee significant projects with the goals of adding value and maximizing tenant satisfaction.

  • New Construction Lease Land Mines

    New Construction Lease Land Mines

    As a tenant, moving into a newly constructed building is exciting but can also cause unforeseen problems if your lease is not carefully drafted. If you are considering new construction, make sure you consider these issues when negotiating your lease:

    Completion Date:

    Establish and agree on the building’s completion date and have a penalty in place if the landlord misses it.  Ideally, both the landlord and the tenant agree on a realistic completion date for the building.  Should the landlord fail to complete the building on time, penalties in the lease could include postponement of the commencement date as well as free rent credits to the tenant for each day of delay not caused by the tenant.  The intention is to make sure the landlord has an incentive to stay on schedule and make the completion of this building a priority.  You should also set a drop dead date at which time you have the right to terminate if the landlord has not yet delivered your space to you.

    Finish Level:

    In addition to specific plans and specifications for your space, establish a clear definition of finish level in the common areas and exterior of the building.  For instance, you might think the common area bathrooms are going to have marble counters and tile floors.  The landlord may be planning on laminate and linoleum.  If this is not agreed in writing before lease execution, then you might be coming out of pocket for any upgrades it desires. More on this here.

    Base Year Expenses:

    If you are signing a full service lease which includes all building operating expenses in the rent, you will pay increases in those expenses over the first year of the lease (the “base year”).  Consequently, it is important to make sure the base year in the lease reflects a fully-assessed, fully-occupied building.  If not, your base year could be artificially low and your total rent expenses will jump after the first year.   Similarly, if you are signing a triple net lease where the tenant pays all expenses over and above base rent, make sure that the landlord’s projected operating expenses upon which you are basing your decision are realistic and achievable.  Otherwise, you will have an unpleasant surprise for the life of the lease.

    Installation of Furniture and Cabling:

    If construction scheduling is tight and you need to complete your build out or installation of tele-data cabling and furniture while the landlord is still constructing the base building or interiors, detail in the lease a date by which you can begin to make your improvements and install FF&E in your space prior to commencement.  Also, if both the landlord’s contractor and your contractor are going to be working in your space at the same time, define the standards of cooperation required of both parties.

    Signage:

    If you have negotiated for signage of any kind – suite, directory, building or monument – insist that the lease exhibits include renderings of the proposed location and style of signage. For instance, is building signage at the top of the building or an “eyebrow” just above the first floor of the building?  Does building signage include multiple tenants’ signs? Can you use your logo or your name be written in a font chosen by landlord?  Renderings will avoid misunderstandings and disputes at the time of sign installation which will benefit both parties. I get into more specifics here.

    We have helped many clients navigate through this process and would be happy to share further thoughts with you.  Please reach out to my team.