Author: Anita Turner

  • How to Review a Lease

    How to Review a Lease

    In 21 years of tenant rep brokerage, I have had the privilege of working with some exceedingly smart real estate lawyers reviewing leases.  [Tom Aggen, Linda Warren, Vytas Petrulis, to name a few.]  I have learned so much from them and think it only fair that I in turn share that knowledge with you.  So, bookmark this page and pull it up next time you need to review and redline an office lease.  Hopefully, it will save you some time.

    Entities and Definitions

    When I receive a draft lease from a landlord, I start at the beginning, checking to ensure that the entity names are correct.  This blog post goes into depth about why it’s important that the landlord entity matches the tax records for the building and how to make sure that is the case.

    Next, in leases, the drafters will frequently define terms that will be used repeatedly within the document. Those terms will be capitalized.  Make sure that there are no “defined terms” that are left undefined.  You can do this quickly by comparing to a “definitions” page in the document or by searching the defined terms to find the corresponding definitions.  If one does not appear, note it in your comments so that the drafting attorney can address.

    Business Terms

    Have the letter of intent or most recent proposal reflecting the terms to which the parties agreed handy while reviewing the lease.  Check that each of the business terms, i.e. term length, rental rate (including any monthly or annual rent payment calculations), space size and location, rent escalations and operating expense base year, is thoroughly addressed and comports with the negotiated agreement.

    Commencement Date

    This subject is a whole blog post unto itself and, unfortunately, not one that I have yet written.  Suffice it to say that you must verify that the commencement date occurs when you bargained for it, whether that be a date certain or upon completion of improvements.  Also ascertain who bears the risk for failure to deliver by the commencement date.  You do not want your company or your client paying rent for space they are not using.  Now is the time to make certain that does not happen.

    Operating Expenses

    In initial lease drafts, some landlords try to include every possible expense in the definition of Operating Expenses that may be passed through to tenants.  Click here to download my “go to” list of operating expense exclusions that I add to every landlord-generated lease I review.

    Insurance Language

    Insurance lease language can be full of landmines.  This will help you avoid them.

    Assignment and Sublease

    All leases address the rights (or absence thereof) of the tenant to assign or sublease the leased space.  This post details the five must-have lease terms relative to assignment and sublease.

    Build Out

    If your lease anticipates any kind of construction in the premises prior to occupancy, it will include, at a minimum, a workletter detailing the parties’ respective obligations for construction of the space.  Start by asking the person who will be responsible for overseeing the buildout on the tenant’s behalf to review it.

    This blog post discusses all of the lease exhibits that should be included along with the workletter to ensure a smooth build out process.   Also, make sure these five interior finishes are addressed to guarantee a Class A appearance.  If you happen to be moving into a newly constructed building, this is a must read.

    Expansion Rights and Rights of First Refusal

    Always secure renewal rights and document them in the lease.  This post explains why.  In light of the new FASB regulations, read this to understand whether you want those renewal options to be at below-market rental rates.  Also, if your renewal term creates a total lease term in excess of 20 years and your lease is in Alabama, you must read this.

    If your new lease includes a right of first refusal, make sure your lease addresses these 5 things.

    Signage

    If you negotiated signage, make sure the lease addresses these issues.

    Almost Done

    When you finish the steps above and a thorough read-through of the lease, make sure that these No Go Lease Terms are not included in the draft lease.  If they are, delete them.  Read the blog post so that you understand why you need to do so and can convey that position to the landlord’s attorney.

    Lastly, while I am an attorney, I am licensed under the California Bar and currently inactive and therefore cannot give legal advice and do not have malpractice insurance.  Consequently, in a perfect world, you will go through the process I detail above and then send your redline to your actual lawyer who will then love you forever and sing your praises because you have saved him/her so much time.

  • How to Avoid the Nightmare of a Missed Notice Date

    How to Avoid the Nightmare of a Missed Notice Date

    When I was in college and grad school, I waited tables to pay my tuition bills.  At that time, my nightmares were either about tests for which I was not prepared or endless tables of customers waiting inordinately long for their food.

    Fast forward to the present.  As a tenant broker, my work-related nightmares are about missing my clients’ lease renewal or termination notice dates.  It can be truly catastrophic for a tenant to miss a notice date and risk forgoing an option to renew or terminate a lease. And, landlords are not likely to let the lapse slide and honor the late notice — especially where tenant-favorable option language is concerned.

    An example

    You lease 10,000 square feet in an office building in Austin, Texas.  You have the right to renew for five years at a 3% increase over your then-current rental rate.  Because you originally leased your space before the market skyrocketed, your rental rate is currently $10 per square foot below market and this option will enable you to enjoy that below market rate for five more years.  If your lease says that you must give landlord 270 days prior notice to exercise this option and you don’t realize until too late that 270 days does not equal nine months, you just missed the notice deadline.  If you then end up with a market renewal rate, you just cost your company $500,000.  Ouch.

    How do you ensure you never miss a date, whether you are the tenant or the broker representing the tenant?

    My solution has been to abstract every lease into a lease administration database licensed by my company.   I then set ticklers to alert me in advance of approaching notice dates.

    Some larger companies already have their leases in lease admin systems, however, I find this is the exception rather than the rule.  Further, often the broker does not have access to the system.  I will happily duplicate the client’s system in order to sleep well at night knowing that I am not going to miss a date.

    How does this work?

    After a lease is fully executed, I make sure it is abstracted into our database.  As part of that process, I set reminder ticklers to give me sufficient advance notice so that I have can notify my client of the approaching deadline and help them figure out how they wish to address it.

    If my client leases 100,000 square feet and they have a right to renew for five years with twelve months’ notice, I am going to set my tickler for at least 18 months prior to the notice date to ensure the client has time to evaluate renewal versus relocation scenarios prior to giving notice.  For smaller spaces and/or shorter terms, ticklers are set closer to the notice dates.

    What do I do when I receive a tickler notice?

    On a renewal, I will look at:

    • My client’s density in the location: Do they have enough space? Too much?
    • My client’s rental rate vis a vis market
    • The availability of relocation options in the market

    I will synthesize the information above into a memo to my client so that they can evaluate their current situation and begin to formulate a strategy with regard to the renewal.  If my client is not yet ready to make a decision, I will reset the tickler for a month or two later so that I am not in danger of forgetting the notice date.  I keep resetting the tickler until my client has exercised or waived whatever right is concerned.

    There are other benefits to having access to my own lease admin files.  I can answer any client questions regarding previously negotiated leases very quickly and accurately.  I can facilitate speedy review of any estoppel forms received by my clients and also monitor their leases for renegotiation opportunities.  For these reasons, my clients readily agree to let me abstract their leases.  And, because this is an application to which only the broker working on the deal has access, there are no privacy concerns as to other brokers or clients.

    If my approach has piqued your interest, I am happy to recommend lease admin programs or discuss my process.  You can contact me here.

  • The Best Rights of First Refusal Address These 5 Things

    The Best Rights of First Refusal Address These 5 Things

    In leasing, when a landlord agrees to give a tenant a right of first refusal (“ROFR”), the landlord is committing that when the landlord receives a proposal from a third party for available space that is subject to the ROFR, the landlord will offer that space to the tenant at the terms offered to third party.  The tenant has the right to accept the offer and lease the space or refuse the offer, at which time the landlord may proceed to lease the space to the third party.

    This sounds simple but in application, it is anything but.  To ensure that there is no confusion after the landlord gives the tenant the right of first refusal option, the following five things should be considered and documented in the lease.

    #1 Term Length

    Landlord and tenant must determine whether tenant may exercise the ROFR at the terms offered by the third party but for a term that is co-terminus with the tenant’s current lease, or whether the ROFR must be exercised for the term length agreed to by the third party.  This can be critical to both parties.  For instance, if the tenant has only two years left on its lease but needs additional space, may the tenant exercise its right on the space for only a two-year term when the third party was prepared to commit to a longer term?

    Or, if the landlord requires that the tenant exercise the right for the same length of term agreed to by the third party, is there a mechanism in the ROFR by which the tenant can extend its existing lease term to be co-terminus with the ROFR space?

    When I represent the tenant, my approach depends on the length and size of the tenant’s initial commitment.  If my tenant is leasing 100,000 square feet of space for a ten-year term and has a ROFR on the balance of a partial floor it occupies, I will push hard to ensure that the tenant has ROFR rights reflective of its importance to the landlord, i.e. extremely favorable.  If my tenant leases 5,000 square feet on a five-year term, I will push to ensure that the tenant has the right to extend its lease to be co-terminus with any expansion space it leases by virtue of a ROFR.

    #2 Applicable Space

    The parties must determine and document which space is subject to the ROFR.  For instance, if tenant has the ROFR on contiguous space and there are 10,000 square feet of vacant space adjacent to tenant, does the tenant have to exercise the ROFR as to the entirety of the space the third party desires to lease?  Or may the tenant exercise the ROFR as to a portion of the space in the third party offer?  Again, this negotiation is influenced heavily the tenant’s relative size and term commitment to the building.

    #3 Continuing or One Time Right

    Is the ROFR ongoing for the entire term of the tenant’s lease, or is it a one-time right?  Consider the situation where the tenant commits to a ten-year term and has a ROFR on contiguous space that happens to be vacant at the time the tenant signs its lease.  If the landlord receives a third party offer one year into the tenant’s term and the tenant does not yet need the space, will tenant’s ROFR endure through the third party’s five-year term such that should the same space become available in five years, the ROFR will reattach?

    Similarly, if the tenant has the ROFR to all space on the same floor as tenant’s premises, if tenant turns down one space, that space is leased to a third party, and another space on the floor becomes available, does the tenant have the ROFR on the second space to become available?

    Another thing to consider in this area is whether the landlord must present the ROFR to tenant again if the terms of the third party offer improve in the tenant’s favor after the tenant turns down the ROFR.  I like to negotiate language stating that if the third party negotiates a deal which is “materially better” than that presented to my tenant originally, the improved deal must then be presented to my tenant.  I will then negotiate the definition of “materially better” but usually I am content with “the effective net rent is >5% lower than the offer initially presented to tenant.”

    #4 ROFR Notice Response Time

    This is key to both the tenant and the landlord.  From the landlord’s perspective, time kills all deals.  If the landlord has to wait fifteen business days after offering the space to tenant on the third party’s terms, there is a very high risk that the third party will get spooked and look elsewhere.  On the other hand, if a tenant is getting close to needing expansion space but is not aware that some may be coming available, the tenant may need some time to evaluate the offer and secure internal approvals to move forward.  The tenant is going to want as much time as possible to evaluate and respond to the ROFR.

    #5 ROFR Space Start Date and Condition

    The landlord and tenant should agree as to whether the third party’s offer terms will govern the commencement date for the ROFR space and the allowance offered by the landlord to build it out, or whether the ROFR language in the lease between landlord and tenant will define these terms.  Allowance needs to be similarly considered as it is largely dependent on the term question addressed in paragraph one above.

    Addressing these five points takes time and effort, however, your client – landlord or tenant – will be immensely grateful to you later when the ROFR process is efficient and conflict-free.  At the end of the day, the negotiated language has to work for both parties based on the needs/leverage each has at the time the right is negotiated.

  • Have You Earned a Gold Star For Client Service?

    Have You Earned a Gold Star For Client Service?

    Client service has always been my biggest focus at work.  You’re thinking “Right.  You’re just writing that because your clients read your blog.”  While that may be true (many of my clients read my blog), my focus on client service is not quite as noble as it sounds.  The truth is that I love a gold star.  I like to be able to point to a client’s success and say “I helped do that!”  A client service focus also ensures that clients keep coming back to me.

    Which brings me to today’s topic: whether you are a lawyer, broker or other service provider, how should you measure client service?  The most obvious way is to ask your clients how you’re doing.  To that end, I’ve already written this blog post about Net Promoter Score surveying.  You can also sit down and interview your clients annually, an approach so valuable that books have been written about it.  Finally, you can track client metrics including retention, growth, and spending.

    Retention

    Client retention is nuanced but still relatively easy to measure in a commercial real estate context.  If a client has a multi-location portfolio, I ask whether I am getting new assignments each year as transactions occur in the client’s portfolio.  I may not have all of a client’s work because of geography, but are they regularly calling me to help with their transactions?

    By this measure, my biggest success is SAIC.  To date, I have represented them (either directly while I worked at JLL, or co-brokering with JLL) in every geography in which I have lived for over twenty years.  I am so grateful that their real estate team continues to trust me to help them achieve their real estate goals in Alabama.

    In the five years I have been at Colliers in Birmingham, my partner and I have lost only one existing client (and that loss was to a business partner of that client).  For every other multi-location client, we have done at least one transaction per year.  For clients with only one location, we track whether we are able to maintain the relationship across each lease term.  While the data tells us that we have a good track record, we know that the second we lean back, we are sunk.

    If you haven’t seen revenue from a regular client for an unusual length of time, it is probably time to ascertain the reason.

    Growth

    Growth by client is tracked differently depending on the service provider’s industry.  In real estate, we track by number of deals.  If we are increasing the number of deals done annually for a client either nominally or as a percentage of the client’s total deals, we are headed in the right direction.  We can’t necessarily track growth in dollars because some deals/locations may be smaller and thus generate less revenue whereas one large transaction can falsely inflate annual growth numbers.

    In law, individual client growth may be tracked either by revenue or by the number of matters handled for a client.  Each firm needs to determine the best metric for their practice.  The key is that whatever the metric chosen, regular tracking allows for measurement and improvement.

    Law firms can also use revenue growth data to compare trends in revenue for one specific client across practice groups.  Is one practice group increasing their revenues with a client while another practice group is losing revenue from the same client?  Such data can trigger an inquiry to determine whether the client is sending that work to a competitor or just does not have as much of that type of work any longer.  Sharing this information with the client team allows them to diagnose and address the issue.

    Client Spend

    Finally, in some industries, growth can be tracked by client spend.[i]  In the legal industry, tracking client spend year over year can quickly indicate whether a relationship is growing or dying.  If your client is a public company, you can check their 10-K statements to determine their annual revenue growth.  If your client revenues are not increasing in rough proportion to their corporate growth, it can be a sign that you are losing revenues to competitors or work is being pulled in-house.  In either case, it is probably time to get busy righting the (relation)ship.  You can also use the data you gather from this exercise to identify your client service successes and then determine how your firm/company served those clients differently than your client service challenges.

    If you have identified other metrics that are helpful for measuring client service and satisfaction, please share them in the comments or give me a call.  I would love to hear about them!

    [i] Office tenant representation growth is not as easily measured by this metric because our fees are paid by landlords so, in a perfect world, our clients never spend a dime compensating us for our services.

  • Big Apple Wisdom Part II: You’re Using That CRM System All Wrong!

    Big Apple Wisdom Part II: You’re Using That CRM System All Wrong!

    Do you use a CRM (client relationship management) software system?  I do, but after attending LegalWeek in New York last week, I have a new perspective on how to do it better.

    Me and Apto

    As most of my readers know, I am an office tenant advisor in the commercial real estate industry. Because it is important for me to keep track of all of my interactions with clients, prospects and other contacts on a daily basis, I log all of them into Apto — a Salesforce CRM software overlay customized to the real estate industry.

    I enter every non-transaction-related meeting date, phone call, voicemail, marketing material sent, etc.  I also enter personal notes about anything from a contact’s school allegiance (college football is everything in the South) to his/her wedding anniversary date.  Then, any time I am going to reach out to that individual, I can easily review our history.  Finally, I use Apto to set ticklers to remind me to stay in touch with people on a regular basis.

    Law Firms and OnePlace

    The legal industry has access to its own tailored Salesforce overlay: OnePlace.  OnePlace integrates time and billing records, client matter descriptions, client contacts, publications, marketing materials and management objectives for evaluation and tracking purposes.  It allows practice groups to set revenue targets, track progress in real time and disburse info to the group. It also helps firms capture each of the contacts they have with a client or prospect.

    While I find CRM systems invaluable and have become a dedicated user, it seems I am rather isolated in this opinion.  Many of my colleagues who have been in commercial real estate for several years have developed their own systems for tracking information and are resistant to entering it all into another database that (in their assessments) is not nearly as functional as their existing systems.  Because I have “bought in,” this frustrates me.  I know we all see huge value in sharing our data to better interact with our mutual clients.

    The Dilemma: The Users Aren’t Using the System

    Which brings me to LegalWeek.  I attended a roundtable aptly titled “Is CRM a Bad Word in Your Firm?  It Doesn’t Have to Be.”  The roundtable was facilitated by two incredibly kind Canadian gentlemen (is that redundant: kind and Canadian?) from Introhive, a data automation service for CRMs that mines and populates contact data so that end users don’t have to.  Sitting next to me at the roundtable was the Marketing Technology Lead from an AmLaw20 firm.

    Tangent: this firm has a person in the “Marketing Technology Lead” position?  This firm is going to light.  It. Up.

    The Solution

    Back to business. I was dying to know how a huge law firm got its attorneys to adopt a CRM system. I asked Marketing Technology Lead (hereafter “MTL”) for his secret.

    His answer: the firm didn’t get the attorneys to adopt it.

    Wait, What?

    The attorneys do not have access to OnePlace to enter their own data.  Instead, they are sent meaningful data analysis by their business development team on a need to know basis.  Here’s where I acknowledge that I (wrongly) thought I knew more than MTL because how could there be any value to a contact database when the attorneys are not entering their contacts or meetings?

    MTL patiently explained to me that giving the firm’s attorneys the ability to enter their own data was (1) significantly more expensive (you have to buy numerous licenses and they aren’t cheap) and (2) hopeless.  Data entry is time the attorneys cannot bill.  Also, they do not want to learn a new software platform.  The reasons attorneys won’t use the platform go on and on.  Thus, if database population were left to the attorneys, the database would sit empty and unused.

    Consequently, MTL said that his firm uses Introhive to mine the firms’ emails (it looks only at the To, From and Subject lines so as not to compromise privacy), billing systems and other databases to gather contacts.  Introhive then cross-references those contact names with other databases to fill in contact information.  And, it regularly verifies this information so that it catches changes in office address, phone number or company.

    Comes the Dawn

    The business development and marketing teams at MTL’s firm then enter every content marketing campaign, client event, pitch, etc. into the database, tagging the appropriate recipients/attendees/contacts.  These teams then use the data to provide attorneys information like which campaigns a particular client reacted to — either by opening an email and clicking on a link or attending a firm seminar or webinar.  This can help the firm as well as the billing attorney better understand a client’s interests and needs and target future marketing efforts more accurately.

    MTL noted that attorneys are welcome to ask the business development and marketing teams to add other useful data to the database as the attorneys become more comfortable with the database’s use and value.

    I am still contemplating how my firm can apply MTL’s method for CRM integration to facilitate wider and more effective use of our database.  Maybe I’ll give one of my new Canadian friends at Introhive a call!

    [Side note: unfortunately, this is not a sponsored post.]

    _______________________________

    Help Me Help You

    Law and other service firm use of CRM databases is an ongoing area of interest for me.  To that end, I welcome anyone willing to share their CRM experiences with me on or off the record to please give me a call.  You can contact me here and I will update this article as I learn about how others optimize CRM use.

  • Your clients like you, but would they recommend you?

    Your clients like you, but would they recommend you?

    The best way to retain your current clients and win new ones (whether in law, real estate or other service industries) is to deliver superior client service.  BTI Consulting publishes a Client Service All-Stars report each year listing the lawyers across America who provide the best client service as identified unprompted by their clients.  I was pleasantly surprised to find my friend Greg Cook, a litigator with Balch & Bingham, on the most recent list.

    People, there are 1.3M lawyers in the U.S.  Only 319 made this list!

    When I congratulated Greg on the Client Service All Star honor and asked him how he thought about client service, he said that it is his job to make sure his client is never blind-sided.  To Greg, this means he not only has to be on top of every aspect of a case when it is in litigation, he also has to know what is happening with his client’s business so he can help that client avoid future litigation.

    The BTI report backs up Greg’s interpretation of client service.  It states that All Stars are defined as such by their clients because they share common traits, among the most important of which are superior client focus and an exceptional understanding of the client’s business.  In his book Law is a Buyer’s Market, Jordan Furlong echoes this sentiment:

    “Nothing will stitch a client closer to a firm than an assured confidence that the firm understands the client and is looking out for its best interests.”  [Emphasis added.][i]

    How can you find out how you’re doing with your clients if you didn’t make a list like BTI’s?

    Many industries and individuals use Net Promoter Scores (“NPS”) to determine whether they are doing a good job for their clients.  NPS is an index that measures the willingness of clients to recommend a company’s service to others.  Clients are asked just one question: “On a scale of 0 to 10, how likely are you to recommend this company’s service to a friend or a colleague?”

    Respondents are categorized as Detractors (scores of 6 or lower) who were not thrilled with the service and could potentially damage the company’s reputation through negative word of mouth; Passives (scores of 7 or 8) who are not enthusiastic enough about the services to actually promote the service provider; and Promoters (scores of 9 or 10) who recommend the company’s services enthusiastically to others.

    Your clients want you to ask them how you’re doing!  (We know; we asked them.  See our survey here.) I encourage you to send the Net Promoter Survey to your clients and then follow up with them to understand where you are falling short and identify opportunities to better serve them.

    Your client service goal should always be to turn detractors or passives into “raving fans” – the ones for whom you did such a good job that they will sing your praises to others unprompted.  To quote one of my favorite muses, Seth Godin:

    “Surprises and vivid action matter far more than we imagine, and we regularly underinvest in them.”

    The Ritz Carlton moments; the small services we provide to clients that they hadn’t even realized they needed; these are the things that will resonate with them far into the future and create those raving fans.[ii]  And we can only provide this kind of service to them if we truly understand them and their businesses… but that’s this article.

    If you need help, give me a call.  I live for this stuff.

    [i] This book is brilliant and worth every penny!  Order it now.  I am not (unfortunately) a paid endorser.

    [ii] Another great strategy to set yourself apart is to make sure you end client interactions on a high note.  A whole article about this appears here.

    [fancy_box color=”Accent-Color”]A Side Note on the Gravity of the Word “Unprompted”


    Consider two scenarios:

    (1) A friend asks you to recommend an estate planning lawyer. You say, “I use Jane Doe.  Here’s her number.”

    (2) At a dinner party, a friend says “Y’all, my husband and I just finished the estate planning process we should have started ten years ago. We put it off forever because we dreaded it so deeply but Jane Doe made it incredibly manageable.  Not only that, she pointed out ways we could better manage our assets to limit our tax liability in the future.  You have to call her!  Here’s her number.”

    Now to put it in context of the BTI survey.  The respondents were asked who they would recommend for legal work and one of them named Greg Cook.  This is much more compelling than simply answering “yes” to the question “Would you recommend Greg Cook for litigation work?”

    Clearly the unprompted recommendation carries more weight.[/fancy_box]

  • Why a rate reduction in lieu of an improvement allowance is a no go

    Why a rate reduction in lieu of an improvement allowance is a no go

    If you do not work in commercial real estate for a living and have gone through the office leasing process, you have probably been confounded by the way many landlords play fast and loose with allowances for tenant improvements while refusing to budge on the rental rate.  In fact, I have been asked frequently by clients if they could trade some of the improvement allowance offered for a rent reduction.

    The answer is usually no and here’s why.

    First, any money offered as a tenant improvement allowance is spent improving the landlord’s asset AND can be depreciated over time.  Double benefit to the landlord.

    Second — and often most importantly — in building valuation, rental rates are everything.

    When an occupied building is sold as an investment property, the buyer is buying the building’s cash flows for the return on investment they will offer the buyer.  Initially, when investors are considering a building purchase, they often use a “cap rate” calculation to determine value.  Note that if the buyer gets serious, they will eventually run a much more complex and detailed financial analyses.

    In a cap rate calculation, the buyer divides the net rent per square foot by desired return to get the value per square foot of the building.  The value per square foot is then multiplied by the building square footage.  [I am grossly oversimplifying the process to make a quick point but my overall approach here is sound.]

    So, if a building charges a net rent of $20 per square foot, the investor wants a return of 9%, and the building is 10,000 square feet, the building will be worth $20/.09*10,000, or $2,222,222.

    Now, say the landlord is offering you $10 per square foot in tenant improvement allowances and you say “we’ll just take the space as is; please Mr. Landlord, drop the rate $2 per square foot for each year of the five-year term instead.”  The landlord is probably going to say “no” and this is why:

    If that landlord is considering selling the building after your lease is signed, and your lease rate is reduced to $18 per square foot, the building value to that same investor is now $18/.09*10,000, or $2,000,0000.  As a result, instead of writing you a check for $100,000 for tenant improvements, the landlord gave up that same amount in rental income, but the building value went down $222,222.

    Building Size (RSF) Rent/RSF Total Rent on 5 Year Term Value/sf @ 9% Cap Rate Total Building Value
              10,000 $20.00 $1,000,000 $222.22 $2,222,222
              10,000 $18.00 $900,000 $200.00 $2,000,000

    Even when a landlord is not considering selling an asset, valuation can be important.  For instance, if the landlord wants to borrow money against the building, or has already done so and has a minimum loan to value ratio, the building value impacts the amount that may be borrowed.

    Rent/RSF Total Building Value Debt Max
    $20.00 $2,222,222 $1,444,444
    $18.00 $2,000,000 $1,300,000


    If this landlord paid the tenant a $100,000 allowance but maintained a $20 per square foot rate, and a had a loan to value requirement of 65%, the landlord would still be better off by $44,444 in borrowing capacity after subtracting the monies used to fund the allowance.

    Some landlords may give tenants that do not want or need an allowance the equivalent value in free rent at the beginning of the term rather than reducing the rental rate.  This is because once that free rent has been used up (in our example, after six months) the building value based on cap rate is maintained at $2,222,222.

    Lease Economics 101 is complete.  Please look for another installment down the road!

  • This is what understanding your client looks like

    This is what understanding your client looks like

    I preach ad nauseum about the importance of understanding your client’s business if you want to provide a service to them.  Ultimately, all clients are buying solutions to their business problems, even if those problems are positive, like too much growth.  But if you don’t truly understand a client’s business, how can you understand their problems, and if you can’t understand their problems, how can you solve them?

    Give me an example, please

    A few years ago, a brokerage firm moved from downtown to midtown Birmingham.  Management’s motivation for moving was not to save money on real estate (they absolutely did not) or to build more progressive space (again, not the case).  Rather, due to the nature of their business (estate planning), the firm had an older clientele for whom downtown was intimidating due to the perceived difficulty in finding parking and the presumed safety risk.  In addition, the firm’s employees who might have benefited from a few extra hours in the office were leaving the downtown location early to beat traffic getting home.

    This brokerage firm relocated to a more suburban location with abundant free parking closer to its employees’ (and clients’) homes and solved both its problems.  Its clients were more comfortable and its associates spent more time in the office producing.

    If the firm’s broker had not understood his/her client’s needs, he/she probably would not have gotten this assignment.

    If your client is a privately held corporation or partnership, understanding a business is slightly more challenging as you cannot rely on public financials.  However, it is still quite doable.

    What does understanding a business mean?

    It means understanding what the client does, for whom and how they get paid.  You also need to understand where a client is in its industry, where it’s going, who its competitors are and what those competitors are up to.

    A case study: Law firm edition

    Let me use as a law firm as an example to give you an idea of the information I think it is important.  This is the information I would gather before a first meeting and the rationale for each piece of information:

    Number of attorneys: 

    How large is this firm?  If possible, also determine how many non-attorney employees work at the firm.  Many metro areas publish Books of List which detail the number of attorneys at most local law firm offices.  Look for a local Book of Lists’ archive to compare the current number of attorneys to past years to determine if the firm is growing or…not.

    Number of partners: 

    How many partners does the firm contain relative to associates.  The leverage ratio affects everything from overhead costs to overall profitability.  It will also give you an idea of the number of decision makers in a firm as most firms consider every partner a decision maker. Speaking of decisions, how are they made?  By an empowered Executive Director and/or C Suite?  By a Managing Partner?  An executive committee?  A board?  Overall partner consensus?  This is probably the most important item to understand relative to law firms as it will often determine the overall strategy of the firm, the nimbleness of decision making, the progressiveness, et cetera.  It will also be a guide as to how you may need to structure your communications with the firm.

    Locations:

    Is this a firm with numerous location across a state? A country? The globe?  Does the firm operate in a “states’ rights” model where each office makes its own decisions, or is it more centralized?  Which locations are growing?  Which were opened most recently?  What is the number of attorneys in each location?

    LLP or PC:

    This is a can of worms I have only recently dived into, but what a can it is!  For instance, did you know that a PC (because it is a corporation) cannot have a mandatory retirement age for shareholders/partners?  This means, on the positive side, mature rainmakers are able to stay in the firm and continue to contribute without any arbitrary age cutoff.  On the negative side, it can result in an inadvertent bias toward short term decision making if the majority of the voting members skews closer to retirement, thereby making decisions based on the near future rather than the firm’s long-term destiny.  An LLP, on the other hand, can include in its partnership documents an age at which partners must sell back their shares.

    Related to entity choice is capital contribution requirement.  If you can find out whether “members” are required to buy into the entity and how significant the buy-in is, you can get an excellent understanding of how the firm funds capital investments, i.e. debt versus equity or cash on hand.

    Primary Industry:

    Insurance defense? M&A?  Energy?  Aerospace? Tech?  The industry in which a firm practices dictates the type of work, how it is billed, where it is done, whether it is cyclical, the margins, the field of competitors and on and on.  I could list variables affected by the area of law practiced for hours.  You get the gist.  This is important.

    Competitors:

    Are competitors local, regional, national or global?  Why does this firm win the business it wins?  When it doesn’t win, who does it lose to and why?  Are competitors more aggressive on fees or do they boast more depth of knowledge in specific areas?  Understanding the competitive landscape will tell you a lot about where a firm sits and where it is going.

    Recruiting:

    Does the firm recruit a large class of first years out of law school each year?  Or does it focus more on lateral recruiting?  Out of which law schools does it recruit?  Recruiting strategy can have a significant impact on the location of law firm offices as well as the design of the space.  Law firms recruiting millennials are likely going to skew more open and collaborative than firms recruiting senior attorneys that are of a generation accustomed to large private offices.

    Extra Credit:

    What has the firm been in the news for lately?  In what causes is the firm active?  What does its C suite look like?  How about its website: recently updated or a forgotten project?

    The net net.

    Yes, I know it takes a good chunk of time to gather this information, but if it makes you more valuable to your client, isn’t it worth the investment?  I surveyed law firm clients (i.e. general counsel) and they told me: “Our outside counsel (law firm) needs to learn about us.”

    Law firm clients are not alone.  All clients wish their service providers understood them better because it saves clients time and adds value and if you aren’t willing to make this investment, your clients will probably find someone who is.

  • Have a Game Plan Before You Call the Plays

    Have a Game Plan Before You Call the Plays

    I have spent 25 years of my life in the commercial real estate world, first as an attorney, then as a broker.  Consequently, I am not messing around when I say that I think real estate strategy is important.  BUT, it should not precede or trump business strategy.  If you don’t know what’s important to your business and where it’s going, how can you possibly find the right office space in the right location and build it out to support your business goals?

    An Example

    Case in point, law firms typically sign 10+ year leases when they build out new offices.  Many firms do not think about real estate strategy (save potentially taking additional space or giving back a little space) until they are about two to three years from their lease expiration dates.  At that time, brokers begin barraging them with phone calls, visits and emails touting how the brokers can save them money negotiating their next lease deal, whether it be a renewal or a relocation.

    Because most law firms don’t have enough real estate to justify a full time real estate director position, the law firm then gins up a real estate committee to study the issue and select a broker.  Usually, this committee considers how much space the firm currently occupies, its projected headcount growth and the firm’s square footage per attorney as compared to its peers.  The committee then decides how much space the firm needs and whether they want to spend the money to move.

    The broker, armed with this information, identifies valid options and works with the firm to get a renewal or relocation deal done.  Somewhere along the way, the firm engages an architect to help them design their new or refurbished space.  If they’re smart and/or lucky, they engage a firm that challenges them to think about HOW they work in their space.  In these instances, the design can be a powerful tool for facilitating a more productive work force or encouraging new behaviors (if you know what behaviors you want to encourage).

    The Problem

    So, you ask, what’s the problem?  Well, what if you don’t know where your firm is going in the next 10+ years?  What if your firm is encouraging innovation that might spawn a new business that uses space differently in three years?  What if your C suite and business staff is growing?  What if you don’t know what your leverage model (partners to associates) should look like in five years?

    The answers to all of these questions can have a tremendous impact on a firm’s space needs.  For instance, if your firm develops an eDiscovery platform, the programmers and developers working for you are going to want a much different office environment than is typical of a law firm.

    If you expand your project management capability, begin outsourcing some functions to legal process providers and reduce the number of associates you employ, your office space needs are going to change dramatically.

    Maybe your firm’s industry focus means that growth will shift to another city completely.

    The Moral

    I realize that there is some uncertainty to any business’ future plans, especially in an industry undergoing as much change as is the legal industry.  The moral of this story is: Think about your firm strategy (and what effect it might have on your real estate strategy) now; not just when you are faced with a lease expiration.

    OK, How Do We Do This?

    Moving forward, my professional focus is shifting to helping law and other professional services firms build real estate strategies that are based on their business strategies.  It includes a deep dive into the challenges and opportunities facing service firms right now and the development of potential strategies to address those challenges and opportunities.

    My approach is NOT “eliminate your law library” or “move your support staff to cities with lower rents and cheaper salaries”.  These are tired and overly simplified solutions proposed by people who do not truly understand service firms.  While it’s true that law libraries have been shrinking for years, they are frequently being replaced with knowledge centers and collaboration spaces; uses are changing, not going away.  And the remote support staff model may be great if (a) your staff is currently based in a city with high rents and/or salaries; and (b) is significant enough in size that a relocation would generate savings that would outweigh the costs; and (c) your operating model does not benefit from the proximity of that staff.   This, clearly, is not true of most AmLaw200 or smaller firms.

    Rather, my approach is to consider such things as the way law firms are evolving as businesses, how they are structured, diversity recruiting and retention concerns, and millennial recruiting and retention concerns.

    My approach includes defining occupancy, economic and workplace behavior goals.  Where appropriate, it includes partnering with appropriate design firms equipped to address workspace optimization.

    After building a business-based real estate strategy, I help firms understand the strengths and weaknesses of their current real estate portfolios relative to that strategy.  Among the many benefits of this approach for service firms is that together we may discover they have opportunities within their current real estate portfolios to make changes that will more quickly enable them to reach their business goals.

    This means looking at real estate independent of expiration date ticklers.  It also means stepping away from a commission-based operating system for me.  I want you to consider me as a partner navigating your firm into the future.  Sound intriguing?  Let’s talk.

  • Should Office Buildings Have Dress Codes?

    Should Office Buildings Have Dress Codes?

    Most days when I head into work in the morning, I am in “business” attire.  The theory is that this renders me appropriately dressed for any client meeting to which I might be called that day.  However, that is not always the case.  For instance, some of my clients are tech companies and I look like the Church Lady from SNL when I show up in pinstripes.

    So, this whole dress code situation can be a problem whether it is self-imposed or company policy.  It gets even more interesting as different industries with different sensibilities on work attire lease office space in the same multi-tenant buildings.
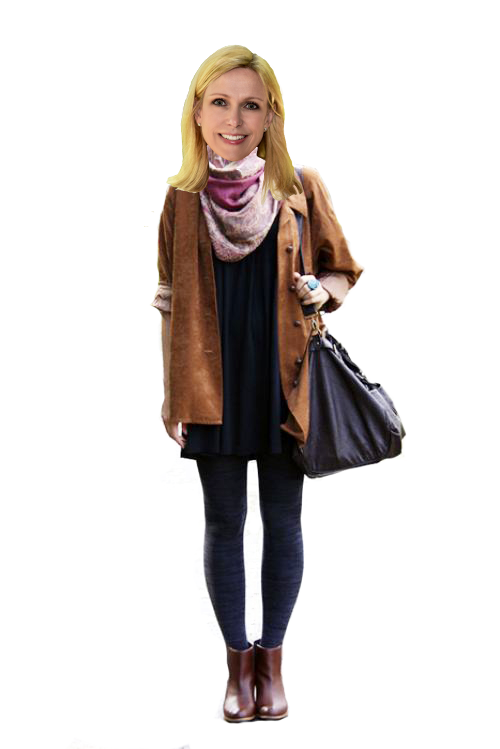
    When I lived and worked in Atlanta, there was a local landlord whose lease included rules dictating “professionally appropriate clothing” in the building.  The same landlord also insisted (in its leases) that any contractors performing construction in the building had to eat lunch in designated areas, presumably so that no one mistook them for actual tenants of the building.  As this was twenty years ago, I am cautiously optimistic that this landlord has evolved in their approach to dress codes.

    I do understand that this landlord wanted its office buildings to be attractive to tenants with good credit and strong businesses and, in the late 90s, such tenants were usually professional services companies, financial institutions and Fortune 500 Companies.  I also understand that many of these desirable tenants had work dress codes and did not want the professional atmosphere they valued to be diminished by other tenants coming to work in flip flops and sweatpants.

    Fast forward twenty years and “unicorn” companies like Uber, LinkedIn, Facebook, and Zappos have no dress codes.  In fact, Google’s employees joke that their dress code is “You must wear clothes.”  And, these companies are arguably the most desirable tenants because of their rapid and well-funded growth.

    So what should a tenant do?  How should a multi-tenant building owner approach the issue, especially in cities other than tech-hubs San Francisco and Austin?  If you are responsible for managing a class A office building in New York City, how do you attract law firm tenants and tech companies alike?  Or do you have to choose between the two?  And if you are a traditional law firm tenant or financial services company, do you care what the other tenants’ employees looks like when they come to work?  Will it affect your clients’ perceptions of your firm?

    I cannot answer these questions as there are as many approaches as there are situations.

    The workplace has evolved extensively in the last ten years.  Business casual encompasses a broad spectrum from nice jeans to the traditional sport coat and khakis.  Consequently, it seems the best approach is to consider the issue (as a tenant or a landlord) before you sign a lease to determine whether it matters to you or affects your business.  If so, perhaps the landlord and tenant could agree to a minimal building dress code (no pajamas?) or, conversely, to a lack thereof.

    On a recent visit to Denver, I was impressed with how easily a white shoe law firm coexisted next to a transplanted San Francisco tech company.  The law firm appeared to have embraced a very comfortable but classy version of business casual while the tech company had embraced a very upscale version of tech casual.  Perhaps over time, the stark differences between dress codes will dissipate.  Until then, give the issue some consideration when choosing your company’s next offices.